a = armcov(x,p)
returns the normalized autoregressive (AR) parameters corresponding to a model of order
p for the input array x. x is
assumed to be the output of an AR system driven by white noise. This method minimizes the
forward and backward prediction errors in the least-squares sense.
Use a vector of polynomial coefficients to generate an AR(4) process by filtering 1024 samples of white noise. Use the modified covariance method to estimate the coefficients.
A = [1 -2.7607 3.8106 -2.6535 0.9238];
y = filter(1,A,0.2*randn(1024,1));
arcoeffs = armcov(y,4)
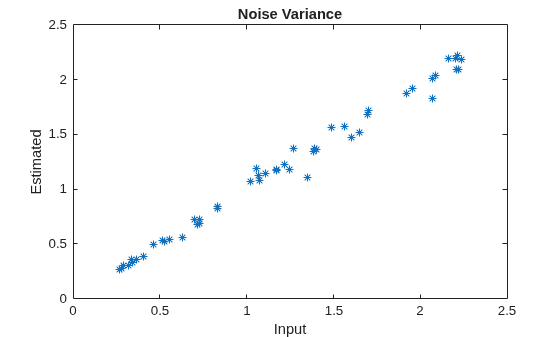
Generate 50 realizations of the process, changing each time the variance of the input noise. Compare the modified-covariance-estimated variances to the actual values.
nrealiz = 50;
noisestdz = rand(1,nrealiz) + 0.5;
randnoise = randn(1024,nrealiz);
noisevar = zeros(1,nrealiz);
for k = 1:nrealiz
y = filter(1,A,noisestdz(k) * randnoise(:,k));
[arcoeffs,noisevar(k)] = armcov(y,4);
end
plot(noisestdz.^2,noisevar,"*")
title("Noise Variance")
xlabel("Input")
ylabel("Estimated")
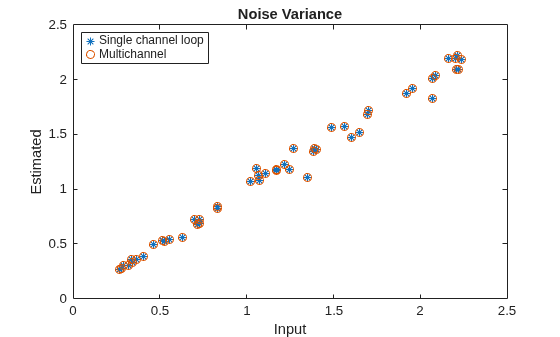
Repeat the procedure using the function's multichannel syntax.
Y = filter(1,A,noisestdz.*randnoise);
[coeffs,variances] = armcov(Y,4);
hold on
plot(noisestdz.^2,variances,"o")
hold off
legend("Single channel loop","Multichannel",Location="best")
Normalized autoregressive parameters, returned as a vector or matrix. If
x is a matrix, then each row of a
corresponds to a column of x. a has p + 1 columns and contains the AR system parameters, A(z), in descending powers of z.
White noise input variance, returned as a scalar or row vector. If x is a
matrix, then each element of e corresponds to a column of
x.
In an AR model of order p, the current output is a
linear combination of the past p outputs plus a white noise input. The
weights on the p past outputs minimize the mean squared prediction error
of the autoregression.
Let y(n) be a wide-sense stationary random process obtained by filtering white
noise of variance e with the system function A(z). If Py(ejω) is the power spectral density of y(n), then
Because the modified covariance method characterizes the input data using an all-pole
model, the correct choice of the model order, p, is important.
You clicked a link that corresponds to this MATLAB command:
Run the command by entering it in the MATLAB Command Window.
Web browsers do not support MATLAB commands.
Sélectionner un site web
Choisissez un site web pour accéder au contenu traduit dans votre langue (lorsqu'il est disponible) et voir les événements et les offres locales. D’après votre position, nous vous recommandons de sélectionner la région suivante : .
Vous pouvez également sélectionner un site web dans la liste suivante :
Comment optimiser les performances du site
Pour optimiser les performances du site, sélectionnez la région Chine (en chinois ou en anglais). Les sites de MathWorks pour les autres pays ne sont pas optimisés pour les visites provenant de votre région.